Thailand’s economic lead is under pressure as Vietnam surges 9.95% in Q3 while Thai growth stays below 2%. Vietnam has 31m more people, a younger workforce and powerful investment momentum, putting a net GDP crossover within reach by 2028–29.
Vietnam is racing towards a historic economic reversal with Thailand after growth surged 9.95% in the third quarter. The kingdom remains richer and marginally larger, but its economy is expanding below 2%. Vietnam already has 31 million more people, a younger workforce and surging industrial investment. Now, IMF projections suggest it could overtake Thailand in total GDP by 2028–29. The transformation marks a dramatic reversal from a generation ago, when Thailand held an overwhelming economic lead. Yet the contest is not over. Thailand retains deeper industrial networks, stronger infrastructure and a substantial advantage in income per person. However, Vietnam’s rapid growth, foreign investment and expanding manufacturing base are closing the gap at extraordinary speed.
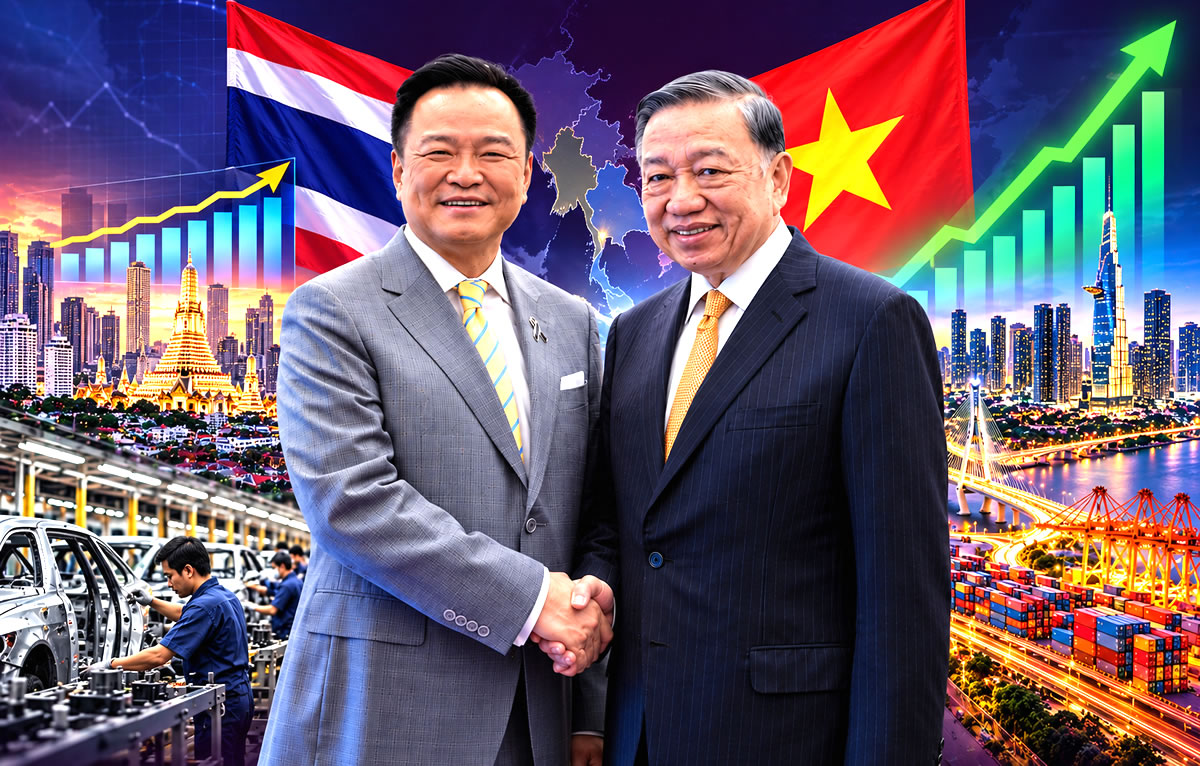
Thailand’s once-commanding economic lead over Vietnam is disappearing at remarkable speed. Vietnam’s economy surged 9.95% in the third quarter of 2026. Thailand, by contrast, remains stuck below 2% growth. The neighbouring economies are now moving at radically different speeds.
Vietnam is expanding roughly four to five times faster than Thailand. Notably, its economy is already almost 90% of Thailand’s size. It also has 31 million more people and a younger population. At the same time, factories, infrastructure and foreign investment are expanding rapidly.
Thailand remains richer per person and retains formidable industrial strengths. However, it has become a persistent slow-growth economy. The kingdom also faces rapid ageing, weaker productivity growth and population decline. Vietnam faces its own pressures, including inflation and a record trade deficit.
Vietnam races forward as growth accelerates and the kingdom’s economic advantage rapidly narrows
Even so, the economic gap is closing quickly. Vietnam could overtake Thailand in total economic output around 2028–29. Thailand’s lead in GDP per person should survive considerably longer. Yet even that advantage is gradually narrowing.
Vietnam’s National Statistics Office reported 9.95% year-on-year GDP growth from July through September. That was its strongest quarterly performance since the COVID-19 pandemic. More importantly, growth accelerated throughout the year. Vietnam expanded 8.15% during the first quarter.
Thereafter, second-quarter growth accelerated to 8.81%. By the third quarter, it had reached 9.95%. Consequently, Vietnam’s economy expanded 9.01% during the first nine months of 2026. Thailand is operating in an entirely different economic environment.
The IMF’s July update projected Thai growth of approximately 1.9% during 2026. Accordingly, Vietnam is presently growing several times faster than Thailand’s projected annual rate. The difference is substantial between the two neighbouring industrial economies. It also follows years of stronger Vietnamese growth.
Thailand expanded approximately 2% during 2025, while Vietnam grew about 8%. As a result, the economic balance between the countries is changing rapidly. Thailand remains the larger economy today. Its remaining margin, though, has become surprisingly small.
Thailand’s $62 billion GDP lead shrinks as Vietnam closes in after decades of faster economic growth
World Bank figures put Thailand’s nominal GDP at approximately $577 billion during 2025. Vietnam stood at approximately $514.7 billion. Thus, Thailand’s advantage was only about $62 billion. Vietnam had already reached almost 90% of Thailand’s economic size.
That position would have appeared extraordinary several decades ago. Thailand industrialised earlier and built one of Southeast Asia’s strongest manufacturing economies. Vietnam started from a substantially lower base. Since then, however, the distance between the countries has steadily disappeared.
The latest figures suggest that process is accelerating. Significantly, Vietnam’s third-quarter expansion was broad rather than concentrated. Industry and construction grew 12.50%, while services expanded 9.54%. Exports of goods and services increased 23.27%.
More strikingly, gross capital formation surged 21.39%. Vietnam is therefore adding investment alongside rapid current growth. Industrial production also accelerated sharply. It increased 16.7% year-on-year during September.
On the trade front, merchandise exports jumped 39.1% that month. September exports consequently reached $59.48 billion. Imports grew even faster, surging 45.8% to $58.21 billion. Despite that increase, Vietnam recorded a $1.27 billion September merchandise surplus.
Vietnam’s investment and industrial surge broadens as exports jump and September trade stays in surplus
The wider nine-month figures were less comfortable. Exports increased 24.5% to $434.3 billion between January and September. Conversely, imports surged 36.7% to $453.72 billion. Vietnam consequently recorded a $19.42 billion trade deficit.
It was the highest deficit on record for the period. In effect, Vietnam’s rapid expansion is creating enormous demand for imported goods and industrial inputs. Energy prices have added another burden. Crude oil import volumes actually fell 13.5%.
Their value, however, increased 14.4%. Separately, refined fuel imports increased 11.5% by volume. Their value surged by 79.3%. Higher energy costs are therefore feeding directly into Vietnam’s import bill.
Inflation has risen as well. Vietnam’s consumer price index increased 5.08% year-on-year during September. Clearly, its rapid expansion carries mounting economic pressures. Investment, nevertheless, continues to rise strongly.
Total investment increased 16.7% during the first nine months. In parallel, the Vietnamese government accelerated infrastructure spending. Foreign capital is arriving simultaneously. Disbursed foreign direct investment reached $21.07 billion between January and September.
That was the highest level for the period in five years. Taken together, public investment, domestic capital and foreign money are expanding quickly. That combination is adding productive capacity at considerable speed.
Record trade deficit and rising inflation expose pressures even as investment and foreign capital surge
New factories require machinery, suppliers, logistics and workers. In turn, expanding industrial clusters generate demand for engineering and specialist services. Infrastructure spending supports that expansion. Vietnam is therefore building additional capacity while recording some of Asia’s fastest growth.
The Asian Development Bank has already raised its Vietnamese forecast. It increased its 2026 projection from 7.2% to 7.8%. The bank cited manufacturing, domestic consumption and sustained foreign direct investment. Even that upgraded forecast trails Vietnam’s nine-month performance.
Vietnam expanded 9.01% between January and September. Beyond that, Hanoi is pursuing full-year growth exceeding 10%. Even 9.95% third-quarter growth therefore falls below the government’s annual ambition. The target shows the pace Vietnam is seeking.
Thailand presents a dramatically different picture. The kingdom is not in recession, while its industrial economy remains substantial. Rather, Thailand is a sophisticated economy struggling to generate strong overall growth. Its established economic strengths remain considerable.
Thailand has a major automotive industry. In addition, it retains substantial electronics, petrochemical and food-processing sectors. Tourism remains another major source of income. Well-developed industrial supply chains have also been built over several decades.
Vietnam builds industrial capacity at speed while Thailand struggles to turn mature strengths into growth
On another front, Thailand possesses mature physical infrastructure. Its financial markets are considerably more developed than Vietnam’s. Manufacturing still represents approximately one-quarter of Thai GDP. The sector also employs more than six million people.
Thailand therefore remains an important Asian manufacturing centre. The World Bank identifies opportunities in several newer industries. These include electric vehicles, batteries and solar equipment. Energy-efficient appliances and advanced green manufacturing provide additional potential.
Recently, electronics exports have benefited from the global artificial intelligence investment cycle. Private investment has also improved in machinery, equipment and data centres. Those strengths, however, have not generated rapid national growth. Thailand has instead remained close to 2%.
The IMF estimated Thai growth at approximately 2.1% during 2025. Its July update then projected only 1.9% during 2026. Manufacturing and services also softened during August. Thailand increasingly combines sophisticated economic infrastructure with stubbornly weak headline growth.
Investment exposes another major contrast. The IMF estimates Thai gross domestic investment at approximately 20.6% of GDP during 2026. Private investment represents around 16.4%. Vietnam, meanwhile, is accumulating capital at a far faster rate.
Thailand retains deep industrial strengths but weak growth and investment leave it trailing Vietnam
Its gross capital formation increased 21.39% year-on-year during the third quarter. Across nine months, total investment increased 16.7%. Meanwhile, realised foreign direct investment exceeded $21 billion. Vietnam is adding factories and infrastructure while expanding at near double-digit rates.
Thailand experienced similar industrial expansion during its earlier high-growth decades. Today, however, it operates from a much more mature economic base. Vietnam still has substantial scope for industrial catch-up. Its lower starting point also permits faster percentage growth.
Demographics add another powerful difference. Vietnam has approximately 103 million people, against Thailand’s 71.6 million. Vietnam therefore has roughly 31.4 million additional people. Its population is about 44% larger.
Crucially, Vietnam’s population is also younger. That provides a larger labour pool for manufacturing and modern services. It also creates a much larger potential consumer market. For multinational manufacturers, Vietnam offers a deeper workforce.
Thailand faces the reverse demographic trend. Its population has already entered decline. IMF-based projections suggest further falls of around 0.1–0.2% annually later this decade. Vietnam’s population is still projected to expand around 0.5% annually.
Vietnam’s faster capital growth and younger population widen its investment and demographic advantages
As a consequence, the demographic gap will continue widening. Thailand is also ageing rapidly. Its working population must therefore support an increasing elderly population. Vietnam retains a younger workforce during its present industrial expansion.
The World Bank identifies ageing as a major Thai structural challenge. Likewise, it points to weak productivity growth. High household debt creates another constraint. Constrained SME dynamism adds further pressure, while fiscal demands are increasing.
Thailand must therefore generate more output from a workforce that is no longer expanding. Vietnam does not yet face that constraint equally. Its larger population provides additional workers and consumers. Population size alone, however, does not determine prosperity.
Thailand remains significantly richer per person. Indeed, this is its strongest remaining advantage in the comparison. World Bank figures put Thai GDP per capita at $8,057 during 2025. Vietnam stood at only $5,066.
Current IMF-based estimates put Thailand at approximately $8,105 during 2026. Vietnam stands at $5,115. Vietnamese GDP per person therefore remains only about 63% of Thailand’s level. Closing that gap will take considerably longer.
Existing projections illustrate the difference. For 2027, Thailand reaches approximately $8,170 per person, against Vietnam’s $5,372. A year later, Thailand rises to $8,392. Vietnam reaches approximately $5,698.
Thailand’s ageing population and weak productivity contrast with Vietnam’s younger expanding workforce
By 2029, Thailand stands at around $8,730. Vietnam reaches $6,010. The difference remains substantial by 2030. Thailand reaches $9,092 per person, while Vietnam reaches approximately $6,323.
By 2031, Thailand reaches $9,498. Vietnam stands at approximately $6,652. Vietnam therefore does not catch Thailand during the existing IMF forecast period. Still, the direction remains towards convergence.
If Vietnamese nominal GDP per person later grows 6–7% annually, the gap steadily narrows. That assumes Thai nominal growth per person of approximately 3–4%. On those assumptions, convergence could occur during the 2040s.
Under stronger Vietnamese growth, the crossover could arrive during the late 2030s. Such long-range estimates carry considerable uncertainty. Exchange rates, inflation, productivity and demographics could shift the dates. The total GDP crossover is much closer.
Earlier IMF estimates put Thailand’s 2026 nominal GDP at approximately $580 billion. Vietnam was projected at approximately $527 billion. Thailand therefore retained an advantage of about $53 billion. That margin then narrowed dramatically.
Thailand keeps income lead per person but Vietnam continues narrowing the gap with faster growth
For 2027, Thailand was placed at approximately $584 billion. Vietnam reached approximately $557 billion. The gap therefore fell to only $27 billion. By 2028, it had almost vanished.
Thailand was projected at approximately $599 billion that year. Vietnam reached approximately $595 billion. Only $4 billion separated them. Then, during 2029, Vietnam moved ahead.
Its economy reached a projected $631 billion. Thailand stood at approximately $623 billion. Vietnam therefore became around $8 billion larger. Subsequently, the projected difference widened further.
Vietnam reached approximately $668 billion by 2030. Thailand stood at about $648 billion. By 2031, Vietnam reached approximately $705 billion. Thailand stood at $675 billion.
Those projections placed Vietnam’s crossover around 2029. Importantly, they preceded Vietnam’s latest acceleration. The country has now expanded 9.01% during the first nine months of 2026. Third-quarter growth alone reached 9.95%.
Accordingly, a crossover during 2028 has become plausible if stronger growth persists. Nominal GDP comparisons, however, are heavily influenced by exchange rates. A stronger baht would increase Thailand’s GDP when measured in dollars.
Vietnam closes the total GDP gap rapidly as IMF projections show Thailand’s lead disappearing by 2029
Conversely, dong depreciation would reduce Vietnam’s dollar GDP. Currency movements could therefore shift the crossover by a year or more. They would not, however, erase the underlying real-growth difference.
Vietnam’s industrial position is also benefiting from changes across Asian manufacturing. International companies have increasingly diversified production beyond China. Vietnam occupies a strong position within that shift.
For one thing, it offers a large workforce and relatively low labour costs. Infrastructure is also expanding rapidly. Geographically, Vietnam sits directly beside China’s enormous industrial supply chains.
That location offers manufacturers another advantage. Companies can diversify production while remaining close to Chinese suppliers. Vietnam also offers extensive links to international markets. Foreign investment figures demonstrate the resulting capital flows.
More than $21 billion in FDI was realised during the first nine months. Alongside that, manufacturing and export capacity continue expanding. The Vietnamese model, however, contains important weaknesses.
Vietnam must increase domestic value added within foreign-owned manufacturing. Imported components reduce the local economic contribution. Foreign companies can also remit profits overseas. Large foreign factories therefore do not automatically create equivalent Vietnamese household income.
Currency shifts could alter crossover timing while Vietnam gains from manufacturing diversification
As part of this challenge, Vietnam needs stronger local suppliers and higher-value production. Technology and components will become increasingly important. Thailand faces a related challenge. It approaches that task from a more developed industrial position.
Thailand already possesses deep automotive and electronics supply chains. It also has decades of manufacturing expertise. Nevertheless, Vietnam is adding industrial capacity much faster. Its capital formation is expanding rapidly, while foreign investment remains strong.
Political structures provide another sharp contrast. Vietnam remains an authoritarian one-party state controlled by the Communist Party. Political opposition is severely restricted. Independent political organisation also faces extensive controls.
International rights organisations report significant restrictions on expression and association. Thailand operates a fundamentally different political system. It has competitive elections and substantially greater political pluralism. Yet Thailand has repeatedly experienced severe political disruption.
Its modern history includes coups and judicial interventions. Political parties have also been dissolved. Additionally, prime ministers and governing coalitions have changed repeatedly. Responsibility for long-term economic policy has consequently shifted frequently.
Vietnam seeks more local value from foreign factories as instability complicates Thailand’s outlook
Vietnam’s one-party structure provides much greater political continuity. Infrastructure and industrial strategies can continue under the same political framework. Major investment programmes can also run across many years.
That continuity does not remove Vietnam’s economic risks. Nor does it guarantee successful investment. Nonetheless, the countries operate under markedly different political and policy environments.
Vietnam combines political continuity with increasingly market-oriented economic development. It also combines export growth with heavy infrastructure spending. Manufacturing investment remains strong. Foreign direct investment provides another large source of capital.
At the same time, Vietnam’s younger workforce supports further industrial expansion. Its larger population also expands the potential domestic market. Thailand still retains major advantages accumulated across decades.
Thai citizens remain considerably richer per person. The country’s infrastructure is mature, while its financial system is deeper. Its industrial networks also remain extensive. Yet those advantages increasingly coexist with weak national growth.
Vietnam remains poorer, but it is adding output several times faster. Its population is 44% larger. Its workforce is younger. Industrial production is expanding rapidly, while investment is rising at double-digit rates.
Vietnam’s political continuity backs long-term investment while Thailand retains deeper strengths
Meanwhile, foreign capital continues entering Vietnam. Infrastructure spending is also accelerating. Its consumer market is considerably larger in terms of population. Thailand faces a much less favourable demographic position.
Its population is shrinking and its workforce is ageing. At the same time, productivity growth remains weak. Household debt creates another economic constraint. Investment has also failed to match Vietnam’s rapid capital accumulation.
The comparison therefore looks dramatically different from only a generation ago. Thailand once held an enormous economic advantage over Vietnam. Vietnam was considerably poorer and substantially smaller economically.
Thailand, meanwhile, became one of Southeast Asia’s leading industrial success stories. That gap has now narrowed dramatically. Vietnam’s economy is already almost 90% as large as Thailand’s.
More importantly, the remaining difference could disappear within two or three years. Existing IMF projections place the crossover around 2029. Those projections, however, came before Vietnam’s latest acceleration.
As things stand, 2028 is now within the plausible range. Thailand should remain richer per person for considerably longer. That distinction is critical to the comparison.
Thailand’s demographic and growth pressures mount as Vietnam closes a lead built over several decades
Vietnam becoming the larger economy would not immediately make Vietnamese citizens richer than Thais. Instead, its much larger population allows total output to overtake Thailand earlier. Even so, Vietnam is narrowing the per-capita gap.
That second crossover will take far longer. Current assumptions point towards the late 2030s or 2040s. The absolute GDP contest, however, is already entering its final years.
Vietnam’s latest 9.95% growth figure has made that increasingly visible. Thailand remains ahead today, but its margin is becoming thin. Vietnam has the larger population and younger workforce.
Above all, it currently has much faster economic growth. Its industrial production is surging, while capital formation is rising sharply. Foreign investment remains strong.
Thailand retains higher income per person. It also retains sophisticated infrastructure and established industrial clusters built across decades. But Thailand is expanding at less than 2%.
Vietnam is presently expanding at close to 10%. That is the central economic contrast between the neighbours. One country remains richer and marginally larger.
The other is adding output several times faster. Thailand’s old economic lead is consequently shrinking. The numbers now put a timeframe on that change.
Vietnam’s larger population and faster growth put Thailand’s remaining total GDP lead on a short timetable
Vietnam could become the larger economy around 2028–29. Thailand’s advantage in income per person should continue for another decade or longer. Even that gap, however, is no longer static.
For decades, Thailand could look north at a substantially poorer Vietnamese economy. That economic landscape has changed. Vietnam is now almost Thailand’s size despite remaining much poorer per person.
Moreover, its 103 million population gives it far greater economic scale. Its younger workforce gives manufacturers a deeper labour pool. Rapid investment is simultaneously creating additional industrial capacity.
Thailand still possesses substantial economic assets. Its 71.6 million population, however, is ageing and beginning to contract. Growth remains weak, while the economic distance between both countries keeps shrinking.
Vietnam’s record is not without serious pressure. Inflation has climbed above 5%. Its nine-month trade deficit has reached $19.42 billion. Energy costs have also surged.
In addition, imports are expanding considerably faster than exports. Yet Vietnam’s economy still grew 9.01% during the first nine months. Thailand remains around a 1.9% projected annual growth rate.
Vietnam nears the economic crossover as Thailand’s industrial strengths fail to deliver comparable growth
The difference is reshaping the economic balance of mainland Southeast Asia. The final crossover has not happened yet. On existing projections, however, it is close.
Thailand retains a $500 billion-plus economy, sophisticated infrastructure and decades of industrial investment. Vietnam still trails substantially in income per person. Nonetheless, the old gap in total economic output is rapidly disappearing.
Vietnam’s third-quarter figures have accelerated that process. Industry and construction are growing at double-digit rates. Capital formation is expanding above 20%. Industrial production is also rising strongly.
Meanwhile, exports and imports are surging as Vietnam absorbs investment, fuel and industrial inputs. More than $21 billion of foreign investment has already been realised.
Thailand’s economy offers no comparable headline growth. Instead, it remains near 2% despite its mature industrial base. The kingdom therefore faces a striking regional reversal.
Thailand entered this comparison far ahead. Vietnam entered it poorer, less developed and recovering from decades of economic isolation. Yet the remaining GDP gap has narrowed to tens of billions.
By 2028, existing projections reduce that difference to almost nothing. By 2029, they put Vietnam ahead. Crucially, those calculations preceded Vietnam’s latest 9.95% quarterly growth.
Thailand keeps key advantages but Vietnam’s faster growth makes the question of overtaking immediate
Thailand therefore retains important advantages, but no longer an overwhelming economic lead. The kingdom remains richer per head and more developed across several sectors.
Vietnam, however, possesses greater population scale, faster growth and stronger demographic momentum. The economic arithmetic has consequently become increasingly difficult for Thailand.
An economy growing near 2% cannot indefinitely preserve a narrow output lead over one expanding several times faster. Currency movements may alter the precise crossover date.
Vietnam’s inflation and trade deficit may also slow its advance. Likewise, stronger Thai investment and productivity could change the growth differential.
The figures currently available, however, show a rapidly narrowing gap. Thailand remains ahead in total GDP today. Vietnam is closing fast.
The question is therefore shifting from whether Vietnam can approach Thailand’s economic size. It already has. Instead, the immediate question is when Vietnam passes it.
Vietnam could pass Thailand by 2028–29 while the kingdom keeps a substantial lead in income per person
On existing projections, the answer is around 2028–29. The per-capita contest remains much further away. Thailand’s roughly $8,000 income per person remains well above Vietnam’s roughly $5,000.
Still, Vietnam continues closing ground through faster growth. Thailand therefore retains a substantial income advantage. Its old regional economic cushion, however, has largely disappeared.
Vietnam is taking Thailand’s quality tourists in huge numbers while Bangkok flails about with crackdowns
PM’s visit to Hanoi strikes a new message of closer ties and partnership between Thailand and Vietnam
A generation ago, the economic distance between Thailand and Vietnam was enormous. Today, Vietnam is almost 90% of Thailand’s size.
Within two or three years, it could be larger.
Thailand’s once-commanding economic lead over Vietnam is no longer measured in generations or decades.
Increasingly, it is measured in years.
Join the Thai News forum, follow Thai Examiner on Facebook here
Follow Thai Examiner on Google here
Receive all our stories as they come out on Telegram here
Follow Thai Examiner here
Further reading:
Thailand’s once mighty tourism industry is failing but now faces further damage from overvalued baht
Rate cut anticipated as outgoing Bank of Thailand governor attends last Monetary Policy Committee
Last minute tweaks in Bangkok as deal is finalised with U.S. However, Thailand may not match Vietnam